Part of our guide to the Lobi Capital. More guides on this topic
A loan is easier to get when the lender can point at the thing it bought.
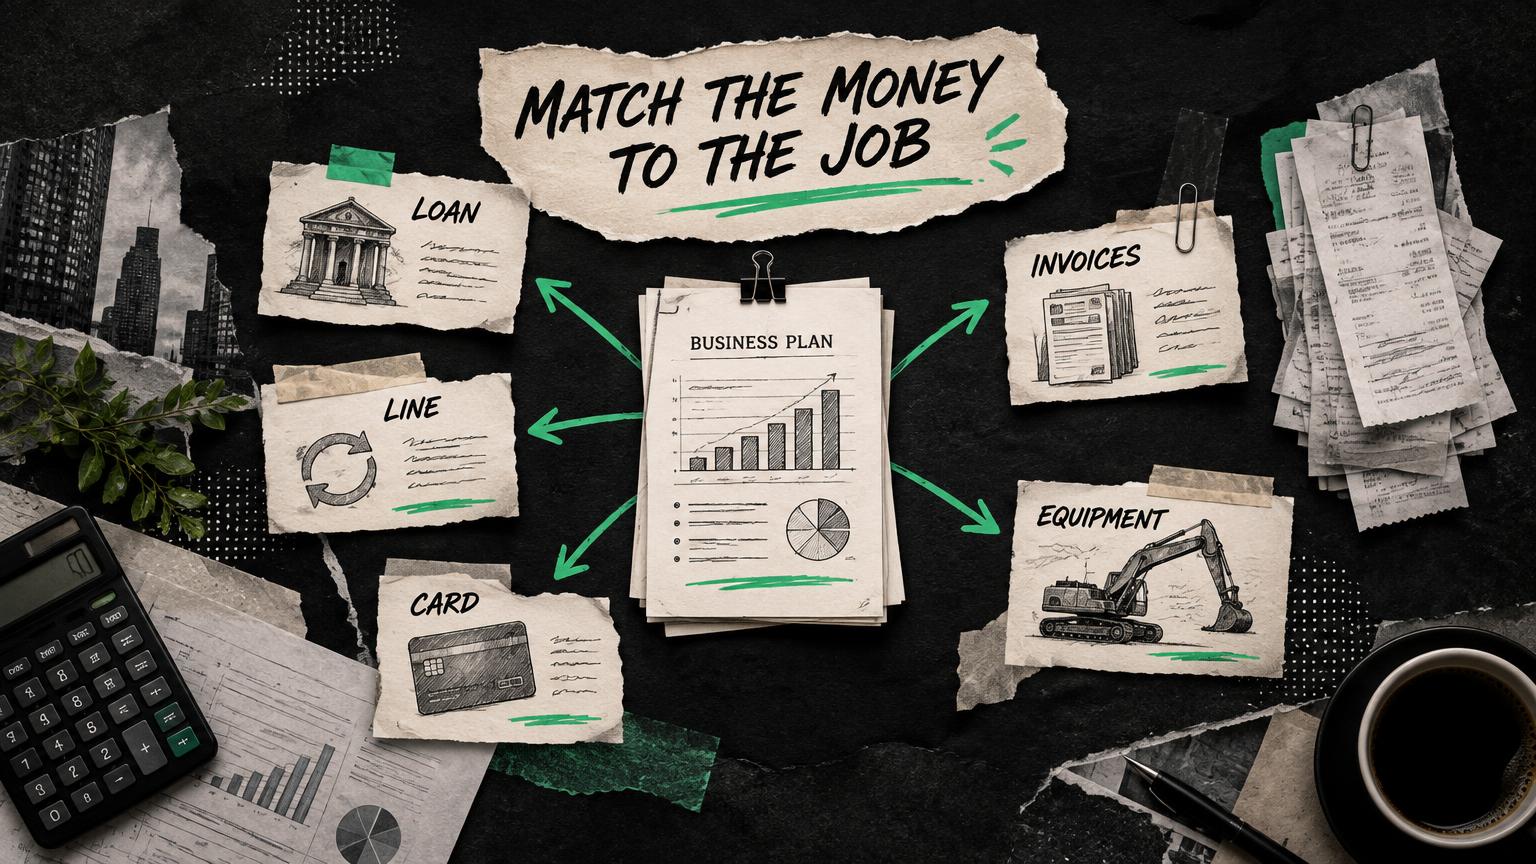
That is the whole logic of equipment financing. The oven, the van, the camera package, the CNC machine, the dental chair. The asset secures the debt, so approval hinges less on your credit story and more on the equipment itself.
Lobi Space is not a lender. This is a plain guide to how the product works, part of our small business funding series.
Loan or lease
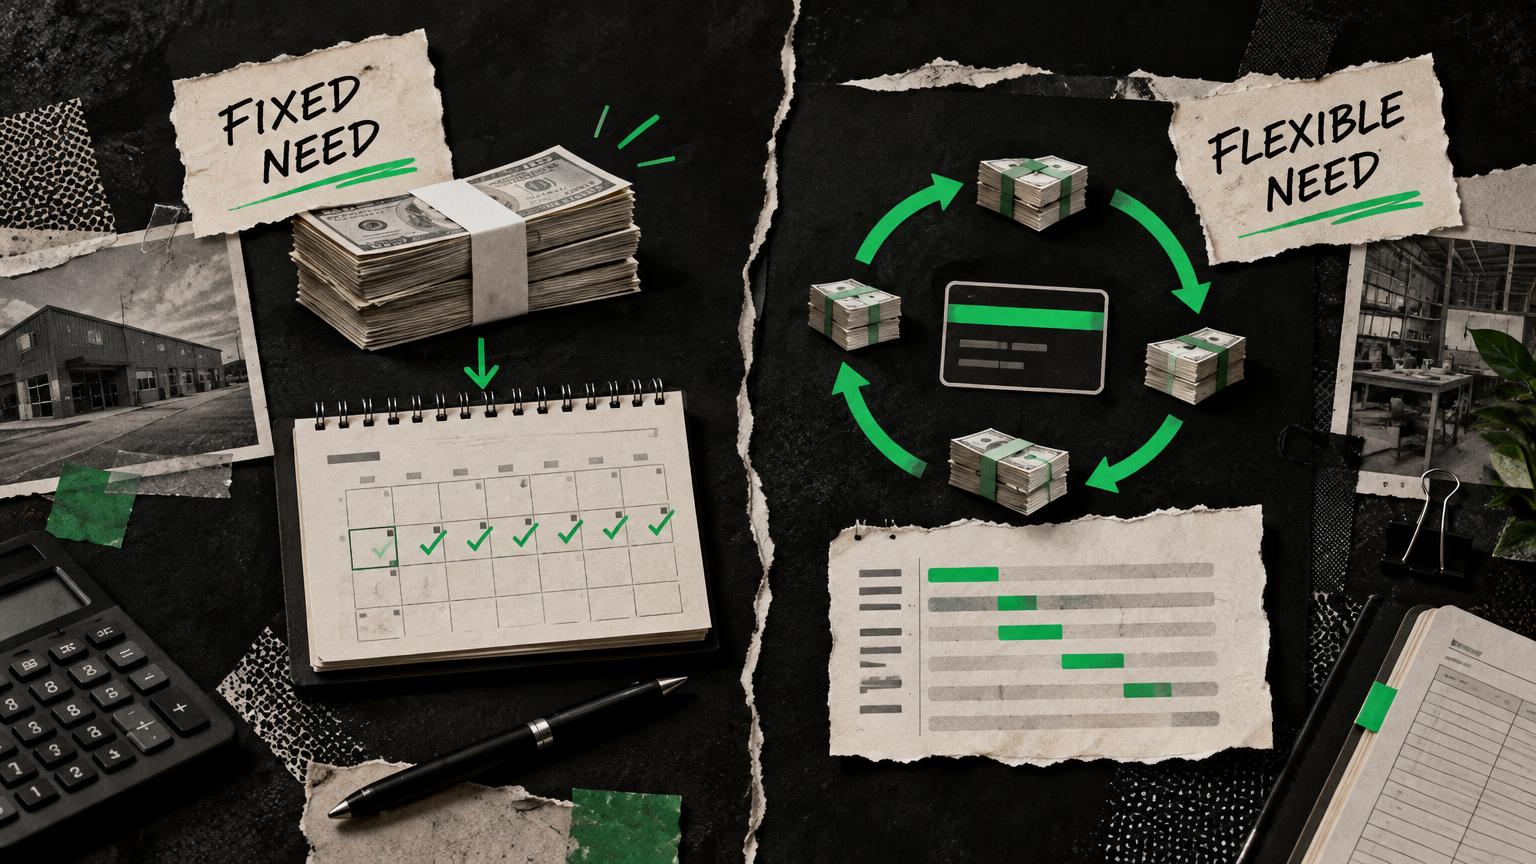
Equipment loan. You borrow, you buy, you own it. The lender holds a lien until you finish paying. Usually a down payment, often a term that roughly tracks the useful life of the asset.
Equipment lease. You pay to use it for a term. At the end you return it, renew, or buy it out depending on the lease type. Lower payments, less or no down payment, and you may not own anything at the end.
The honest test is how long the asset stays valuable to you. Machinery you will run for a decade favors owning. Technology that will be outdated in three years often favors leasing.
Tax treatment differs between the two, and it is worth having the vocabulary before you call your accountant. When you buy, Section 179 lets many businesses deduct the full purchase price in the year the equipment goes into service, up to an annual cap that phases out once total purchases pass a spending threshold, and bonus depreciation covers ground Section 179 does not. Both sets of numbers move with legislation, which is why IRS Publication 946 is the thing to check rather than any figure printed in an article, ours included. A true lease works differently: the payments are generally deducted as rent as you go. Ask your accountant before you choose, not after. Knowing the terms just means that conversation takes ten minutes instead of forty.
What lenders look at
- The equipment. What it is, whether it holds value, new or used, and whether there is a resale market.
- Time in business and revenue, though thresholds are often gentler than unsecured products.
- Personal credit of the owners and usually a personal guarantee.
- The vendor quote or invoice. Lenders commonly pay the seller directly.
- Down payment, frequently a percentage of the purchase price.
Because the asset carries part of the risk, this is one of the more accessible products for businesses that get declined elsewhere. And if the private offers still look rough, equipment is exactly what the SBA's 504 and 7(a) programs were built to fund, with longer terms and rates most equipment finance companies will not match. Slower, more paperwork, and worth it often enough that we wrote a separate guide to qualifying.
The lien is public, and it can outlive the payoff
"The lender holds a lien" is doing quiet work in that earlier sentence, so here is what it means in practice. The lender files a UCC financing statement, usually called a UCC-1, with the Secretary of State. That filing is a public record. Anyone, including your bank and whoever you ask for money next, can search Illinois UCC filings and see exactly what is encumbered.
Two things to read before you sign. First, the collateral description. It should name the equipment, not "all assets of the debtor." A blanket filing quietly encumbers everything you own and can block the next loan you actually need. Second, the ending. When you finish paying, the lender is supposed to clear the filing with a termination, and busy lenders forget. Search your own business after payoff, and if the lien still shows, ask for the termination in writing. Five minutes of follow-through there saves a scramble in the middle of your next closing.
When it beats a general loan
- The purchase is a single identifiable asset with a real market value.
- The asset produces revenue you can forecast.
- You want to keep your line of credit free for operations.
- You would rather not pledge everything else you own.
When it does not fit
- Soft costs. Installation, training, permits and delivery are sometimes excluded or only partly financed. If the install needs city sign-off, start at Chicago's business portal and price that side before assuming the loan covers it.
- Fast-depreciating or highly specialized gear with no resale market.
- Situations where you actually need working capital and are dressing it up as an equipment purchase.
Run the math on the asset, not the payment
Salespeople quote monthly payments because payments sound small. Do this instead.
1. Total cost of the financing in dollars, including fees and down payment.
2. Additional monthly profit the equipment produces, conservatively estimated.
3. Months until the asset pays for itself.
4. Whether you still want to own it at that point.
If the asset does not clear its own payment inside its useful life, it is not an investment. It is a cost with a schedule.
Get your file straight first
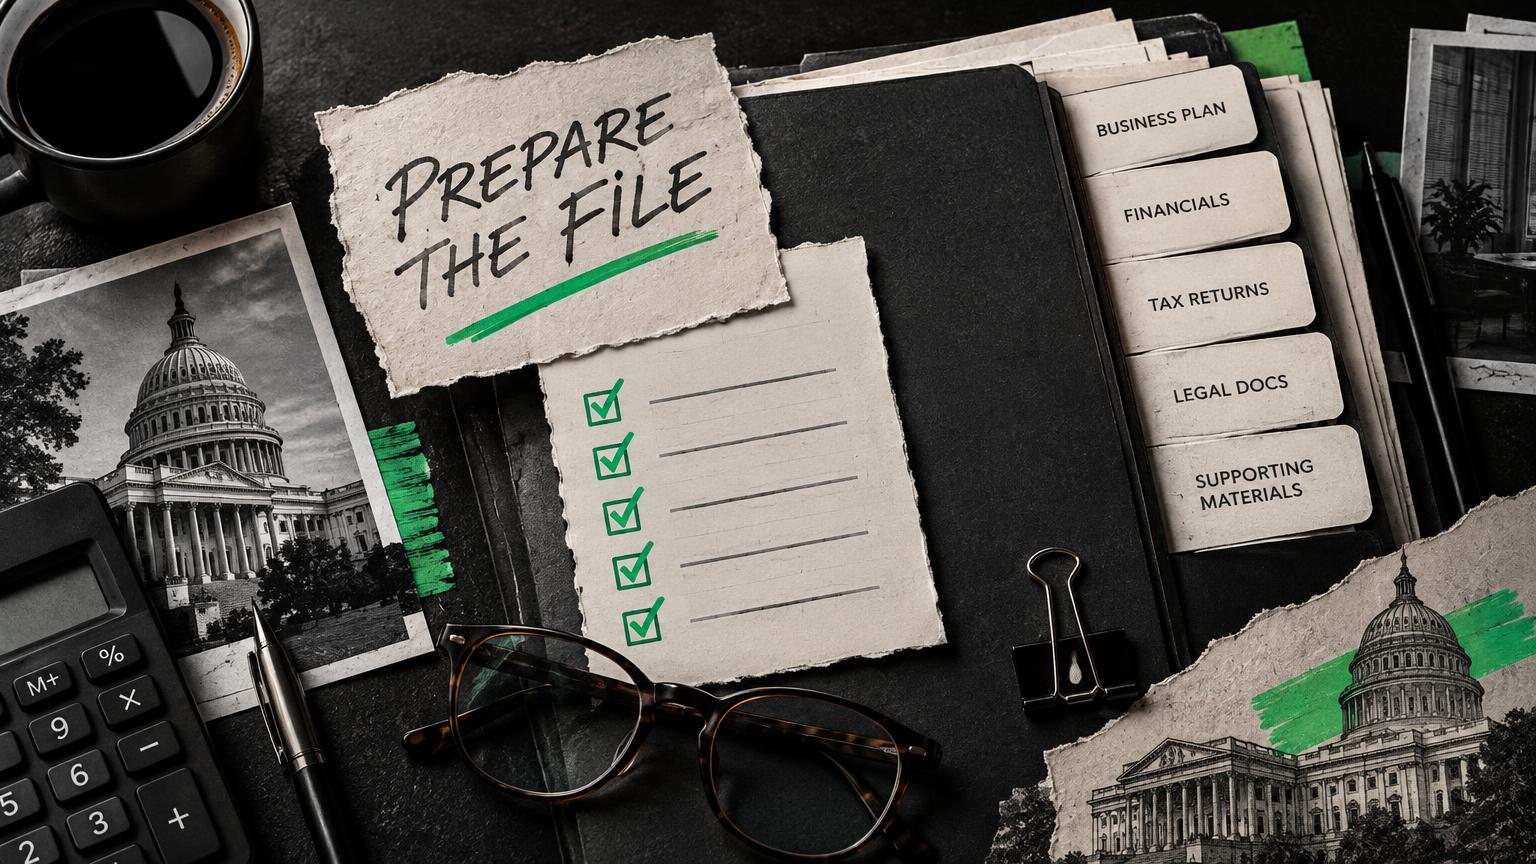
Equipment lenders verify the business, the vendor and the asset. Clean, consistent records move faster. One business address across your filings, your bank and your application avoids the verification back and forth, which is one of the quieter reasons businesses use our virtual office in Chicago.
When Lobi Capital opens, you will be able to describe what you are buying and see which paths may fit. Join the launch list to hear when it does.
Frequently asked questions
Can I finance used equipment?
Often yes, though lenders care about age, condition and resale value. Terms on used assets can be shorter and down payments higher than on new equipment.
Do I need a down payment for equipment financing?
Frequently, yes. Many lenders ask for a percentage of the purchase price, and stronger applicants sometimes qualify for less. Leases often require little or nothing up front.
Is leasing or buying equipment better?
It depends on how long the asset stays useful to you and how the tax treatment works for your business. Long-lived assets usually favor owning, fast-changing technology often favors leasing. Ask your accountant.
Will equipment financing show on my personal credit?
The application usually involves a personal credit check and a personal guarantee. Whether the account itself reports to consumer bureaus varies by lender, so ask before you sign.